ServicesNon-Trucking Liability (Bobtail)
Non-Trucking Liability (Bobtail) Insurance in Arlington
Your motor carrier covers liability while you run under their dispatch. When you are off the clock in your own truck, that coverage usually stops. We set up non-trucking liability that fits your lease, explain where it ends and get the certificate to your carrier.
What This Coverage Does and Who Needs It
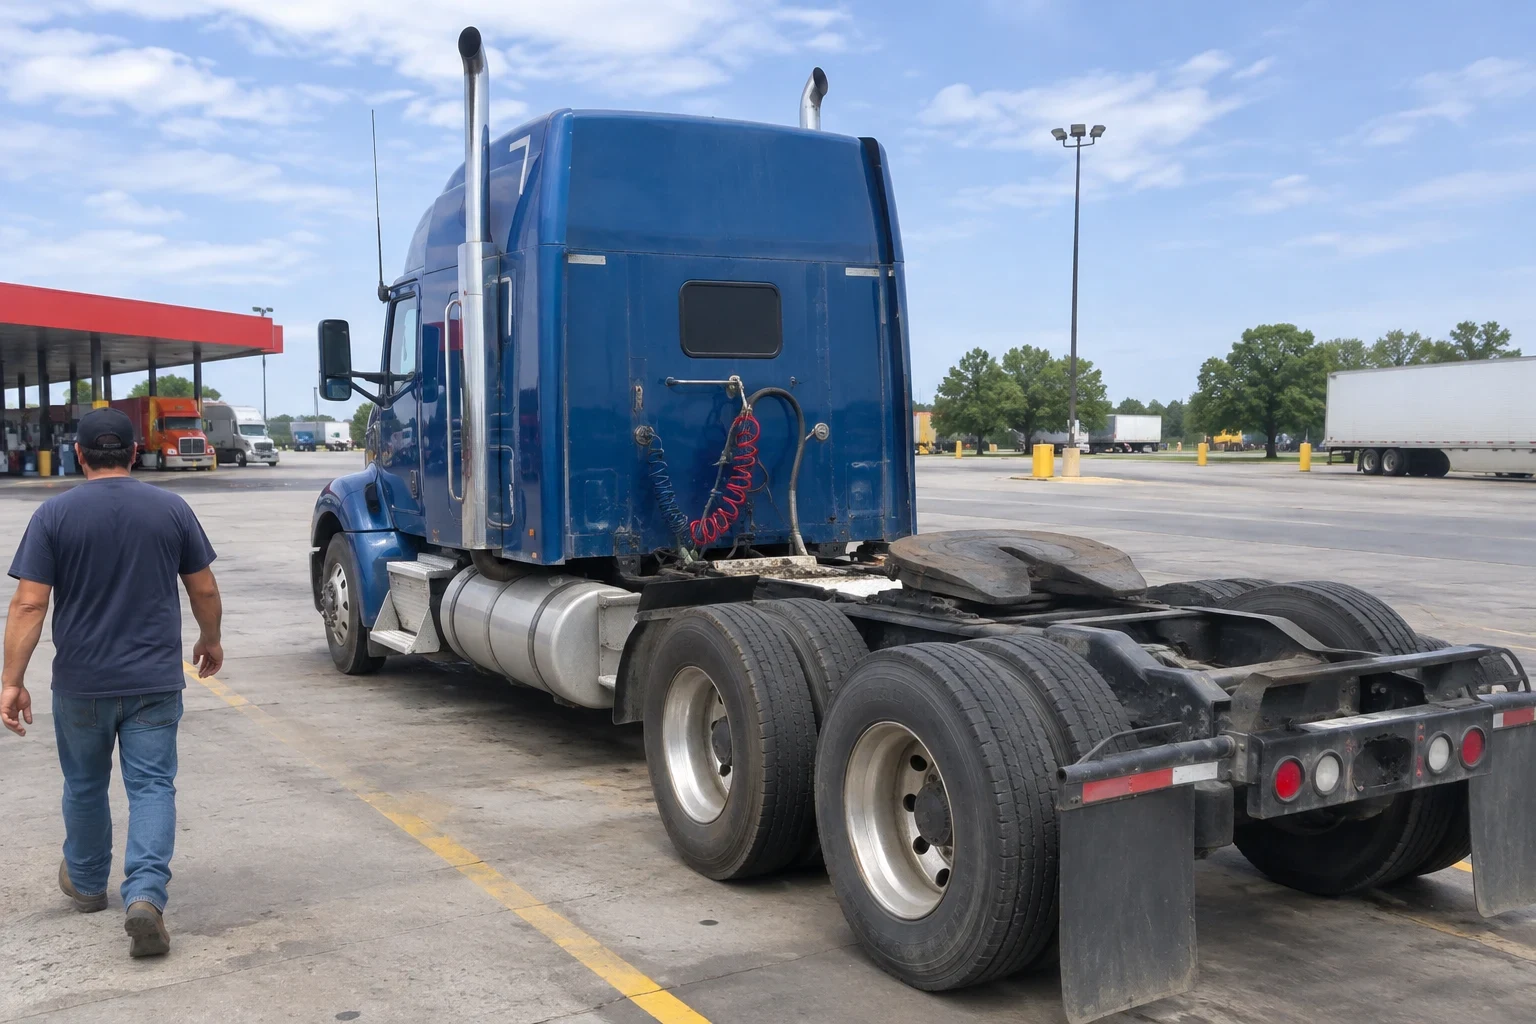
Non-trucking liability, often called bobtail, is for owner-operators leased onto a motor carrier. It pays for injury or damage you cause to other people while driving your truck for reasons that are not part of a load. Driving home after a run, taking the truck to the shop on your own time, or moving it on a weekend are the usual examples.
Most lease agreements require it. The carrier's primary liability follows the truck while you are under dispatch, and this policy covers the gap when you are not. If you run under your own MC authority, you need primary auto liability insurance instead, not this.
A cheap policy is not much use if the wording leaves you uncovered on the trips you actually make. We read your lease, ask how you use the truck between loads and pick coverage that still works a year from now, after you switch carriers or change routines. That is cheaper over time than finding the gap after a claim.
What We Handle for You
- 01
Lease review
We read the insurance section of your lease agreement. It usually sets the liability limit and says who has to be named on your certificate.
- 02
Quotes from more than one company
We get quotes from the insurance companies we work with and lay them side by side. You see the premium, the limit and the wording that matters.
- 03
Plain talk on exclusions
Some policies only cover you when no trailer is hooked up. Others cover you off dispatch with or without a trailer. We tell you which one you are looking at before you pay for it.
- 04
Certificate of insurance
Once the policy is bound, we send the certificate to your carrier with the right names on it. If you sign on with a new carrier later, we issue a new one.
- 05
Help with the rest of your coverage
Non-trucking liability does not fix your own truck after a wreck. If you need that, we can talk about physical damage insurance at the same time.
Questions about Non-Trucking Liability (Bobtail)?
Call(817) 402-2551Signs You Need Non-Trucking Liability
You are signing a lease
Most carriers will not put you on the road without proof of this coverage. They usually want the certificate before your first load.
Your truck goes home with you
If you drive your truck home between runs, to the shop or anywhere off dispatch, you need liability for those miles.
Your carrier deducts it from settlements
Some carriers sell their own program and take the premium out of each settlement. That can be fine. It can also cost more, or end the day you leave that carrier. It is worth comparing.
You are changing carriers
A new lease can mean a new limit or different names on the certificate. Check the policy before the switch, not after.
You are getting your own authority
Once you run under your own MC authority and DOT number, this policy no longer fits. Call us early so we can move you to the right coverage with no gap.
How It Works When You Call
- 1
We talk it through
Call us and tell us who you are leased to, what you drive and how the truck gets used between loads. Have your lease handy if you can. We can also meet at our office or set up a video call.
- 2
We check the lease terms
We look at the limit your carrier requires and how they want the certificate written. This keeps us from quoting something your carrier will send back.
- 3
You get your quotes
We walk you through each quote: premium, limit, what is excluded and how payment works. You pick what makes sense for your operation.
- 4
We bind and send the certificate
After you decide, we bind the policy and send the certificate of insurance to your carrier. You get a copy too.
- 5
We check in at renewal
Before the policy renews, we look again. If your driving record, carrier or truck changed, the coverage may need to change with it.
What Affects Your Premium
Non-trucking liability usually costs less than primary liability because it only covers part of your driving. The price still moves around a fair amount from one driver to the next. These are the things that matter most. The lowest premium is only a good deal if the wording covers the miles you really drive.
- The limit your lease requires
- Your carrier sets the minimum. A higher limit costs more, but going below what the lease asks for is not an option.
- Your driving record and experience
- Tickets, accidents and how long you have held a CDL all affect the rate. A clean record over several years helps.
- Where the truck is parked
- Insurers look at where the truck sits between loads. A truck parked in Arlington is rated differently than one kept in a small rural town.
- The type of truck
- A tractor, a straight truck and a pickup pulling hotshot loads are each rated differently.
- Policy wording
- A bobtail-only policy that drops coverage when a trailer is attached can cost less. It also leaves more trips uncovered, so we explain the tradeoff.
Questions About Bobtail Coverage
Is bobtail insurance the same as non-trucking liability?
People use the names for the same thing, but policies are written differently. Some only cover you with no trailer attached. Others cover you any time you are off dispatch, trailer or not. We tell you which kind a quote is before you buy it.
Does it cover me while I drive to pick up a load?
Usually not. Once you are dispatched, even if you are empty and heading to the shipper, that counts as business use. The carrier's primary liability should cover that trip. Non-trucking liability is for the miles that have nothing to do with a load.
Will it pay to fix my truck after a wreck?
No. This is liability coverage, so it pays for harm you cause to other people and their property. Damage to your own truck is covered by physical damage insurance, which many owner-operators carry alongside it.
Should I buy through my carrier or get my own policy?
Either can work. A carrier program is easy because the premium comes out of your settlements. Your own policy can cost less and stays with you if you change carriers. We can quote your own policy so you have a number to compare.
Who sells this coverage?
An agent licensed for property and casualty insurance, which is the license our agency holds. We quote it, bind it and send the certificate your carrier asks for.
Do you work with drivers outside Arlington?
Yes. We work with owner-operators in Grand Prairie, Mansfield, Euless, Bedford and the rest of the area. Most of the work happens by phone, so we can help wherever your truck is parked.
Get Your Lease Covered the Right Way
Tell us who you are leased to and how you use the truck off dispatch. We will quote coverage that fits the lease and explain where it ends.