ServicesHotshot Truck Insurance
Hotshot Truck Insurance in Arlington, TX
We set up insurance for hotshot runners: the pickup, the trailer, the freight and the liability that comes with hauling for hire. We look past the first-year premium to deductibles, cargo limits and exclusions, so the policy still makes sense after a claim or a renewal.
What hotshot coverage is and who needs it
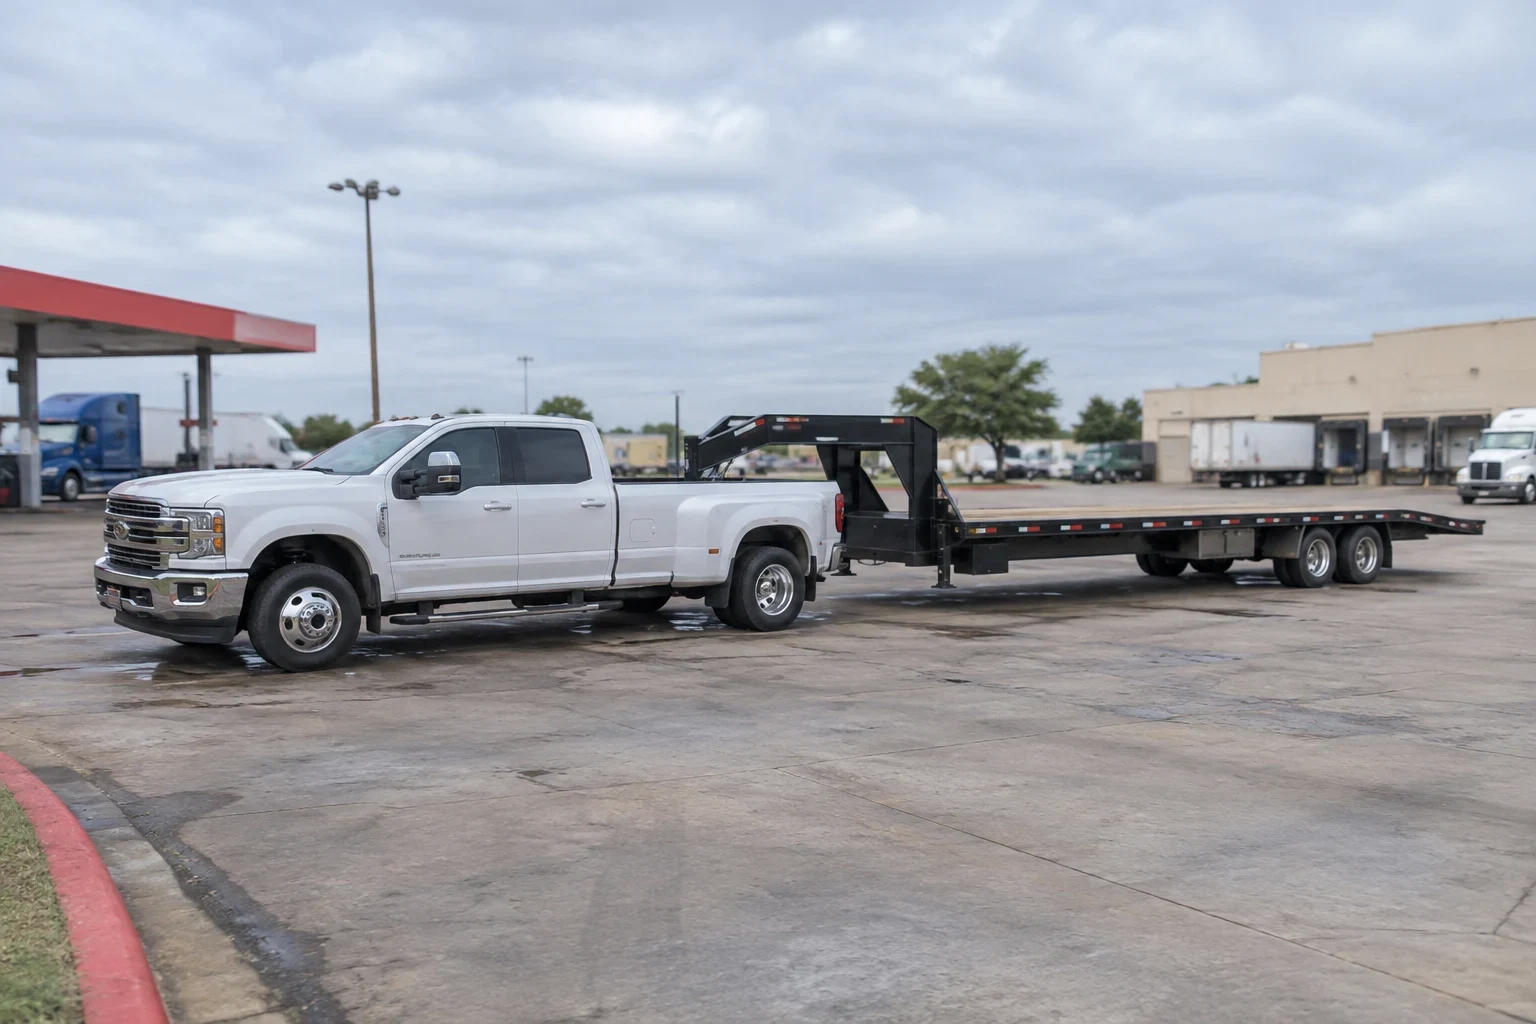
Hotshot work means a one-ton or medium-duty truck pulling a gooseneck or bumper-pull flatbed, usually on tight deadlines. Once you haul for hire, a personal auto policy stops covering you. You need commercial coverage, and if you run under your own DOT number and MC authority, the right filings have to be on record before you can legally take loads.
We are licensed for property and casualty insurance, and hotshot is a big part of what we quote. Most of our hotshot customers want three things on one plan: primary auto liability, cargo coverage and physical damage on the truck and trailer. Some also need non-trucking liability if they are leased on to a carrier.
The cheapest quote is not always the best buy. A low premium with a high cargo deductible or a narrow list of covered goods can cost you more than it saved the first time a load shifts. We show you both sides before you pick.
What we put together for a hotshot policy
Primary auto liability
Covers damage and injuries you cause to others while hauling. Brokers and shippers check this first, and federal rules set the floor for for-hire carriers.
Cargo coverage for open-deck loads
Hotshot freight is usually strapped down in the open: pipe, equipment, steel, machinery. We read the exclusions with you, because some policies limit unsecured loads, certain commodities or theft from an unattended truck.
Physical damage on truck and trailer
Pays to repair or replace your pickup and gooseneck after a wreck, theft or weather damage. We list the trailer separately so it is not left off by mistake.
Filings and certificates
We handle the federal filings tied to your MC authority and send a certificate of insurance to the brokers you work with. If your weight puts you under Texas intrastate rules, we cover that filing too.
Non-trucking liability when leased on
If you run under another carrier's authority, their policy covers you on dispatch. Non-Trucking Liability (Bobtail) Insurance fills the gap when you are off the clock in the same truck.
Signs it is time to look at your hotshot coverage
You are still on a personal policy
If the truck hauls paid loads, a personal claim can be denied outright. That is the biggest risk we see with new hotshot runners.
A broker wants a higher cargo limit
Heavier equipment loads often come with higher cargo requirements. If you are passing on good freight because of your limit, it is worth a look.
You are leaving a lease for your own authority
Going independent means you need your own liability and filings in place. Our New Authority Truck Insurance page covers that step in more detail.
You bought a new trailer
A newer gooseneck is worth more and may not be listed on your current policy. Call before the first load on it, not after.
Your renewal jumped
Premiums move with claims, driver records and the market. We can check whether the increase is fair or whether another setup fits your operation better.
How we work through it with you
- 1
A phone conversation
We ask what you haul, how far you run, who drives and what the truck and trailer are worth. Have your DOT number, MC authority and driver license info handy if you have them.
- 2
We shop the markets
Not every insurer writes hotshot, and some avoid newer authorities. We take your details to the ones that do and compare what comes back.
- 3
We walk through the quote line by line
You see each coverage, limit and deductible, plus the exclusions that matter for your freight. We point out where paying a bit more now saves money on the first claim.
- 4
Binding, filings and your certificate
Once you choose, we bind the policy, get the federal filings on record with the insurer and send a certificate of insurance to your brokers. Then you can start booking loads.
What moves the price of hotshot insurance
No two hotshot quotes come out the same. Insurers look at the driver, the equipment and the freight, then weigh how long you have been running. We explain which of these you can change and which you just have to wait out.
- Driver record and experience
- Years of commercial driving and a clean motor vehicle record carry a lot of weight. A recent ticket or accident can move the premium more than anything else on this list.
- Time under your authority
- Brand-new authorities pay more because there is no track record yet. Rates usually ease as you build clean years.
- What you haul and how far
- Oilfield pipe, heavy equipment and long interstate runs rate higher than local runs with light freight. A run that stays around Arlington and Grand Prairie prices differently than one crossing several states.
- Truck and trailer value
- Physical damage cost follows what the equipment is worth. Higher deductibles lower the premium, but only pick one you could actually pay out of pocket.
- Limits you choose
- Higher liability and cargo limits cost more up front. They also open up brokers and loads that lower limits shut you out of.
Hotshot insurance questions we hear
Something not covered here? (817) 402-2551
Will my personal truck policy cover me if I only haul a few loads?
Usually not. Most personal policies exclude hauling goods for pay, even part time. If a claim happens on a paid load, the insurer can deny it. You need a commercial policy before the first load.
Can I get coverage with a brand-new MC authority?
Yes, though fewer insurers will quote it and the premium is higher at first. Driving experience helps a lot here. We shop the companies that write new hotshot authorities and show you what each one offers.
Does physical damage cover my gooseneck trailer?
It can, but the trailer has to be listed on the policy with its value. We list the truck and trailer separately so both are covered. If you swap or add trailers, let us know so the policy stays current.
How much cargo coverage do brokers want?
It depends on the broker and the freight. Many set a minimum, and equipment or machinery loads often call for more. Tell us who you haul for and we will match the limit to what they require.
Do I need different coverage if I am leased on to a carrier?
Your carrier's policy usually covers liability while you are under dispatch. You still need non-trucking liability for personal use of the truck, and often physical damage on your own equipment. We can sort out which pieces are yours to carry.
Get your hotshot coverage set up right
Tell us what you haul and where you run. We will lay out the options side by side so you can see the cost now and what it means over the next few years.