ServicesDump Truck Insurance
Dump Truck and Construction Truck Insurance in Arlington
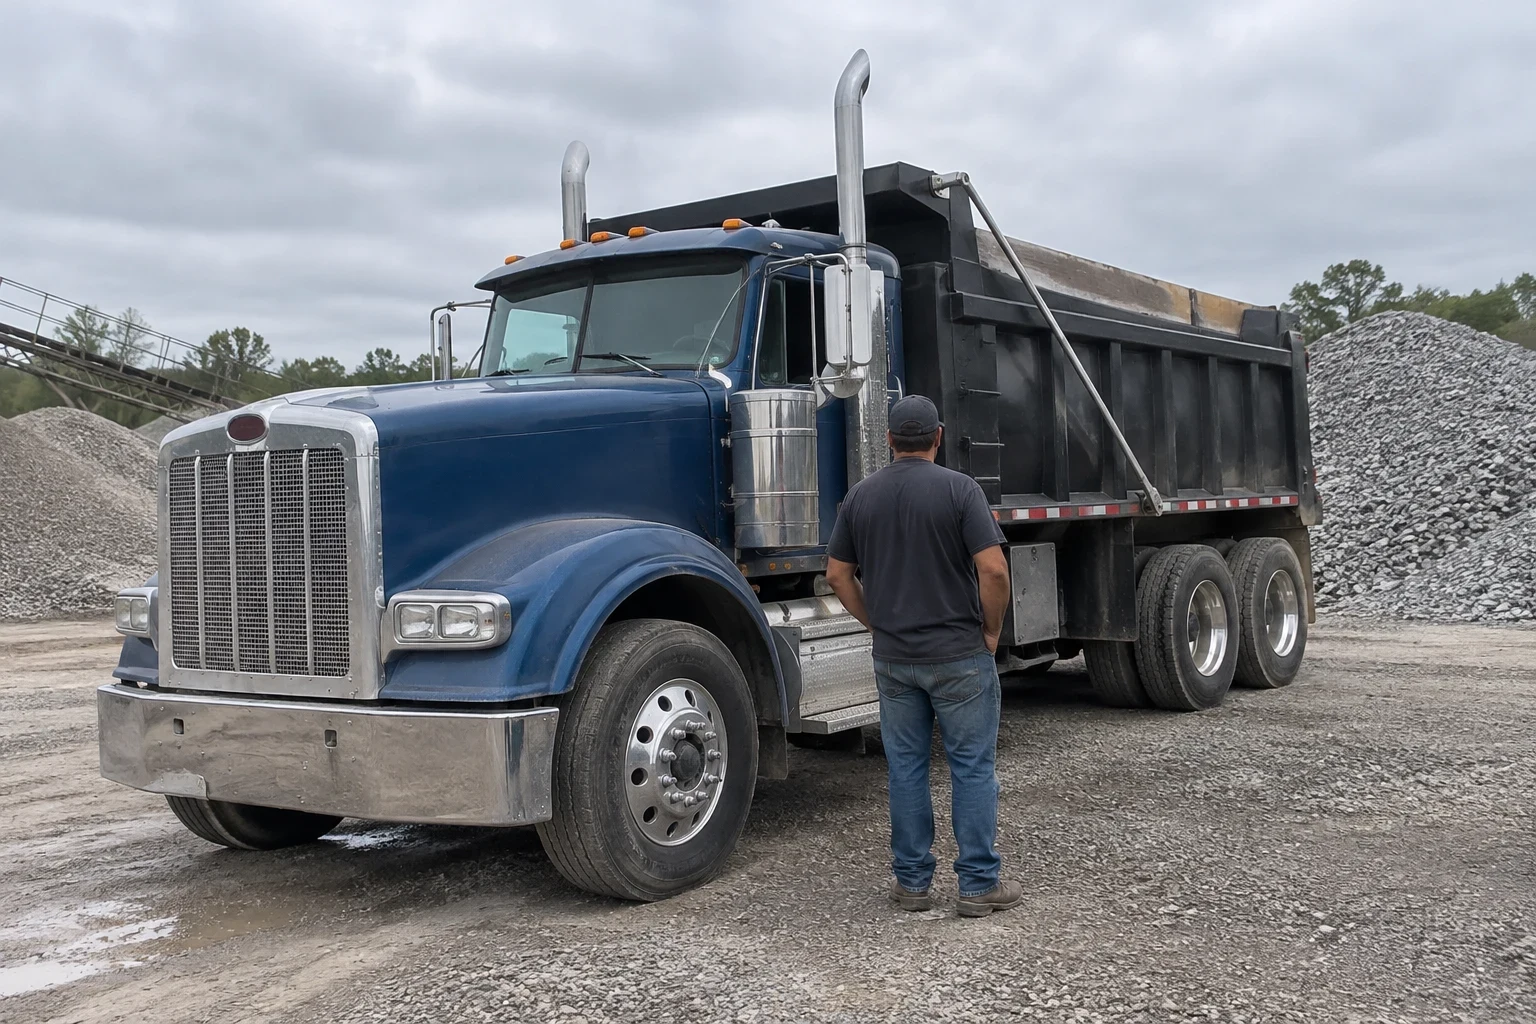
Dump trucks live a rough life. Short hauls, loose rock, soft ground and contractors who want paperwork before you roll on site. We set up coverage that fits that work, so the premium you pay now still makes sense two years from now.
Coverage built for haul work, not highway freight
A dump truck runs a different day than a long-haul tractor. Most of the miles are local. A lot of time is spent backing up, raising the bed and dumping on ground that may not be level. Rocks fly. Windshields crack. Underwriters price all of that, and a policy written like it's for a dry van can leave gaps right where you need cover.
We're licensed for property and casualty insurance, and we write policies for owner-operators with one tandem dump, small outfits running a few trucks, and construction businesses that haul their own material. We look at what you haul, how far you go from the yard and who you haul for. Then we shape the coverage around that.
Our approach is simple. The cheapest quote today is not always the cheapest year. We show you how deductibles, truck worth and coverage limits play out over the life of the truck, so you pick something that still works after the first claim or the first contract renewal.
What a dump truck policy usually includes
Primary auto liability
This pays for injuries and damage you cause to others while driving. It's the coverage most contractors and filings ask about first. See our Primary Auto Liability Insurance page for how limits work.
Physical damage on the truck and body
Collision and comprehensive for the chassis and the dump body. We make sure the stated amount includes the bed, hoist and any added equipment, not just the cab and frame. Our Physical Damage Insurance page goes into more detail.
Radius and use set correctly
Local, intermediate or long haul changes the rate. We list your real radius so the premium matches the work and a claim isn't questioned later.
Certificates for contractors
General contractors often want a certificate of insurance before you get on site, sometimes naming them on the policy. We issue those and keep them current when your policy renews.
Filings when you need them
If your operation needs a DOT number or state motor carrier registration, the insurer may have to file proof of coverage. We handle those filings with the carrier.
Cargo coverage, if it applies
Dirt and base rock often don't need it. Hauling for someone else or moving equipment might. We'll tell you plainly which case you're in, and our Motor Truck Cargo Insurance page explains the rest.
Signs your current policy may not fit your dump work
A contractor rejected your certificate
If a GC sent your certificate back asking for different limits or wording, your policy may be short of what job sites now expect.
Your truck's insured amount is out of date
A new bed or hoist adds to what the truck is worth. If your policy still lists the old number, a total loss pays the old number.
You're hauling farther than you used to
Taking jobs out past Mansfield or Cedar Hill when the policy says local radius can cause trouble at claim time.
Your deductible would hurt
A high deductible lowers the premium. But if one cracked windshield or tipped bed would sting your cash flow, the savings may not be worth it.
You added a truck or driver
New units and new drivers need to be on the policy before they work. Growing outfits can look at our Fleet Truck Insurance page too.
How getting covered works
- 1
A phone or video talk
We ask about your trucks, what you haul, how far you run and who you work for. Have your VINs, driver list and any loss history handy. You can also stop by our office.
- 2
We shop the market
We take your details to carriers that write dump and construction trucks. Not every company wants this class of work, so the field narrows fast.
- 3
Side-by-side options
We walk you through each quote line by line. Premium, deductibles, limits and what each one costs you over a couple of years, not just the first payment.
- 4
Bind, file and certify
Once you choose, we bind coverage, handle any needed filings and send certificates to the contractors you work for.
What moves the price
Dump trucks tend to cost more to insure than many other trucks because of the short trips, the job-site exposure and the damage these units take. Your quote depends on a handful of things we'll go through on the phone. Some you can change, some you can't.
- Driver records and experience
- Clean MVRs and years behind the wheel of a dump truck count a lot. One driver with recent tickets can lift the premium for the whole policy.
- Truck value and age
- A truck worth more costs more to cover for physical damage. Older trucks may cost less to insure but more to keep running, so we look at both.
- Radius and what you haul
- Local aggregate work prices differently than hauling demolition debris or equipment across the region.
- Limits and deductibles
- Higher liability limits cost more, and contracts may require them. Deductible choices shift cost between the premium and your pocket at claim time.
- Loss history
- Past claims follow you for several years. A clean stretch can help at your next renewal.
Dump truck insurance questions
Something not covered here? (817) 402-2551
Do I need cargo coverage to haul dirt and gravel?
Often not. Low-value bulk material is usually not worth insuring, and many policies treat it that way. If you haul equipment or material owned by a customer who requires cargo coverage, that changes. We'll sort out which applies to you.
Does my policy cover the truck tipping while dumping?
Physical damage coverage usually responds to a rollover or tip while dumping, minus your deductible. Read the exclusions with us, because some policies limit certain off-road use. We'll point out anything that matters for your work.
What will a general contractor ask for?
Most want a certificate of insurance showing your auto liability limit. Some want to be named on the policy or want specific wording. Walk us through their requirements on the phone and we'll check if your policy meets them before you start the job.
I'm just starting out with one truck. Can you help?
Yes. New outfits are harder to place, so the first quote may be higher. Our New Authority Truck Insurance and Owner-Operator Truck Insurance pages cover what to expect in that first year.
Can I lower my premium later?
Often, yes. A clean claims record, steady drivers and an up-to-date truck list all help at renewal. We review the policy with you each year so you're not paying for coverage that no longer fits.
Get your dump truck coverage set up right
Have your truck info and driver list ready. We'll go over your options by phone and show you how each one holds up over time.