Trucking Insurance in Arlington That Still Makes Sense at Renewal
We set up primary liability, cargo coverage, physical damage and bobtail policies for owner-operators, new MC authorities and small fleets. We show you what each choice costs now and what it means a year from now. Trucking businesses from Grand Prairie to Mansfield get their quotes from us by phone or video.
- Licensed for property and casualty
- Line-by-line quote review
- Filings handled with you
- By phone or video
Coverage for Trucks That Work for a Living
We are licensed for property and casualty insurance, and trucking is the work we focus on. That covers commercial trucking insurance and primary auto liability, plus physical damage, motor truck cargo, non-trucking liability (bobtail) and trailer interchange. We also build policies around how you run: owner-operator, new authority, fleet, dump and construction, hotshot and box truck. Pick the one closest to your operation and start there.
Commercial Trucking Insurance
Liability, physical damage, cargo and filings built around your trucks, with costs compared over several renewals, not just this year.
Primary Auto Liability
Required liability coverage for trucks under your own authority, with limits matched to your broker contracts and federal and state filings handled for you.
Physical Damage Insurance
Collision and comprehensive coverage for your tractor, straight truck or trailer, with insured amounts and deductibles set to fit the equipment's age.
Motor Truck Cargo Insurance
Cargo coverage built around what you actually haul, with limits brokers accept and exclusions spelled out before a claim, not after.
Non-Trucking Liability (Bobtail)
Liability coverage for leased owner-operators when the truck is off dispatch, matched to what your lease says and how you really use the truck.
Trailer Interchange
Physical damage coverage for trailers you pull but don't own, set up to match your interchange agreements and the trailers you actually haul.
Owner-Operator Insurance
Coverage for one-truck operators, leased on or under your own authority, set up so the premium still makes sense at renewal.
New Authority Truck Insurance
Insurance for motor carriers with a fresh DOT number and MC authority, from the liability filing to cargo and physical damage coverage.
Fleet Truck Insurance
Coverage for carriers running several trucks and drivers, set up so adding units, swapping drivers and pulling certificates stays simple.
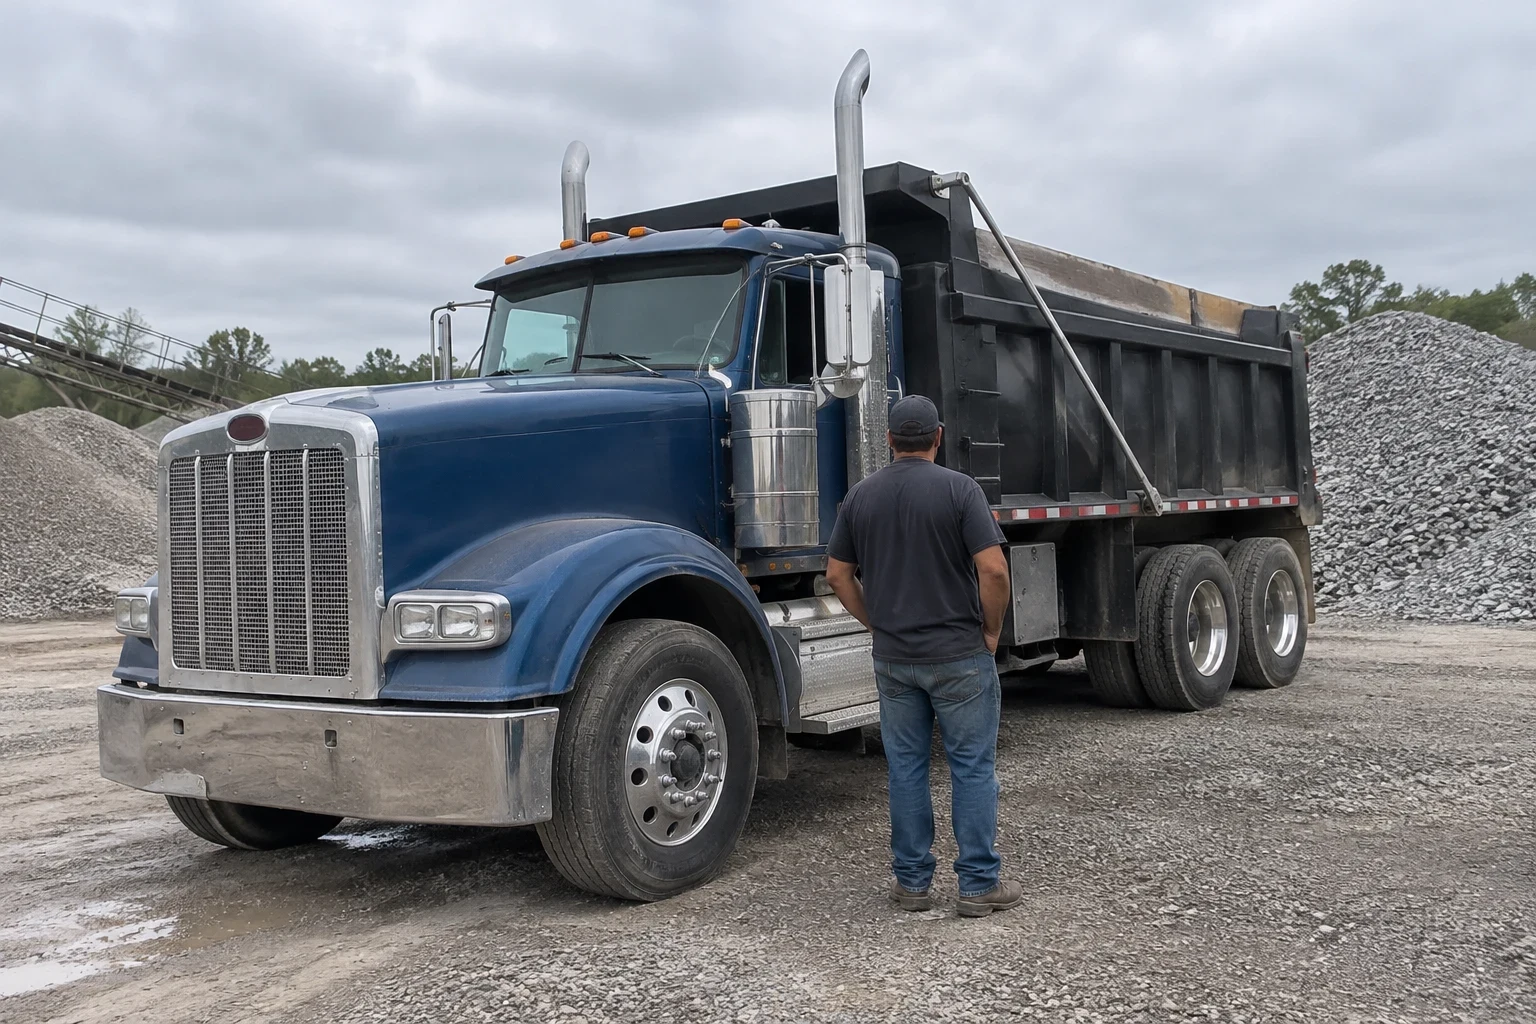
Dump Truck Insurance
Coverage for dump trucks, end dumps and job-site haulers, set up for short-radius work, contractor certificates and the wear construction trucks take.
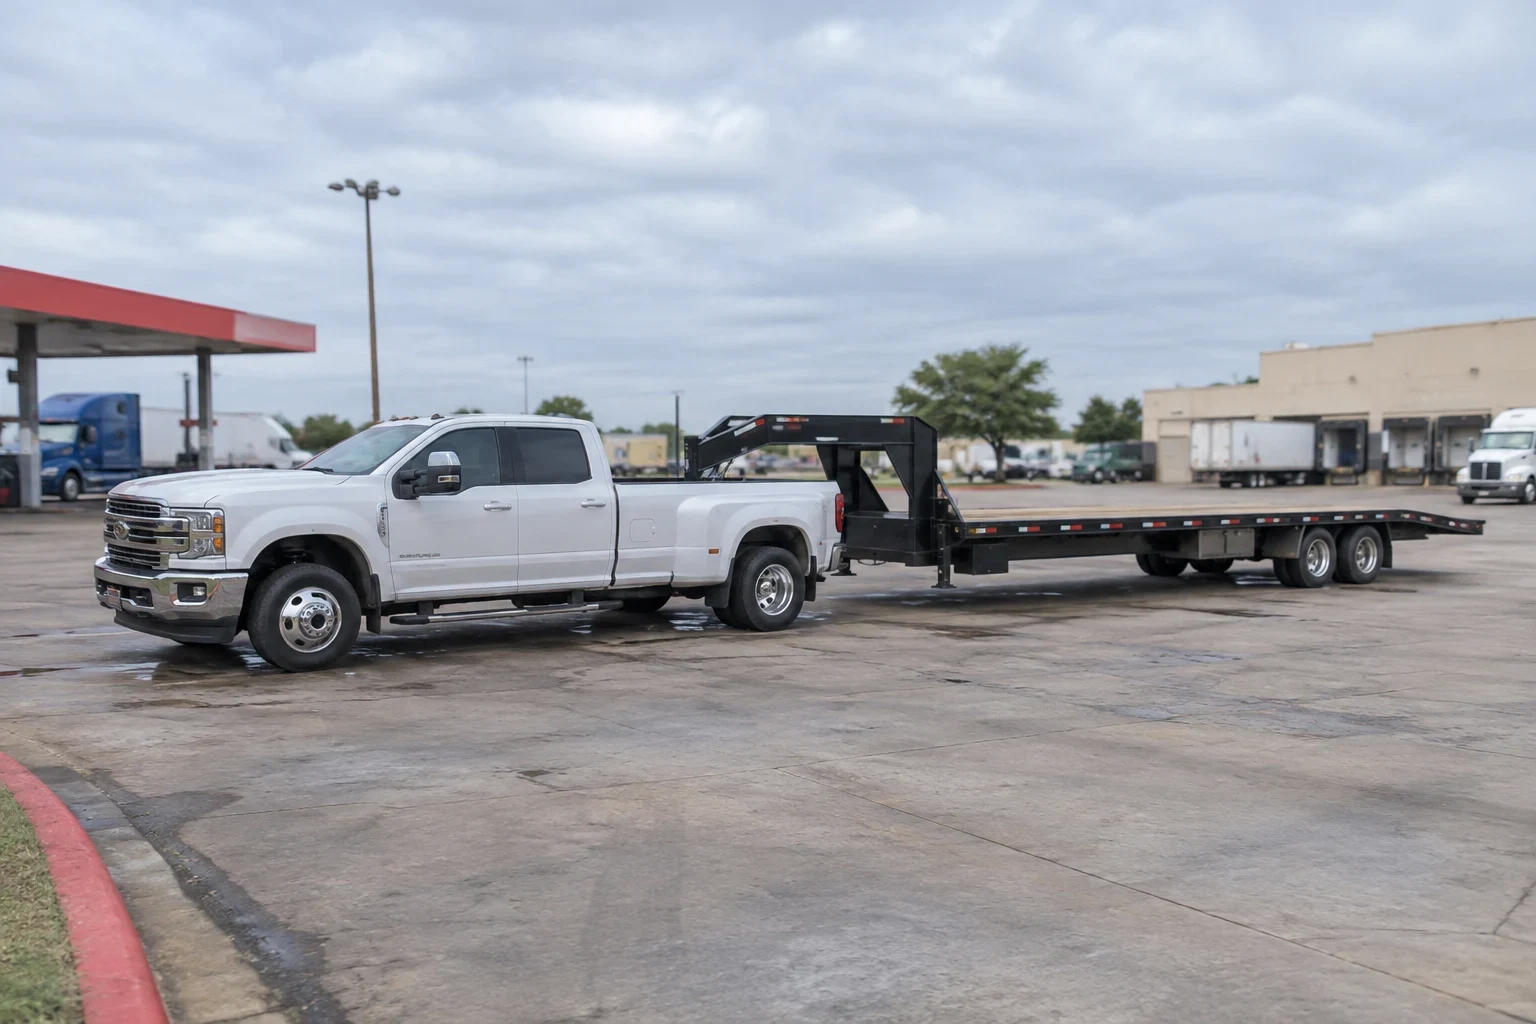
Hotshot Truck Insurance
Coverage for one-ton pickups pulling gooseneck and flatbed trailers, with liability, cargo and physical damage set up to match the loads you haul.
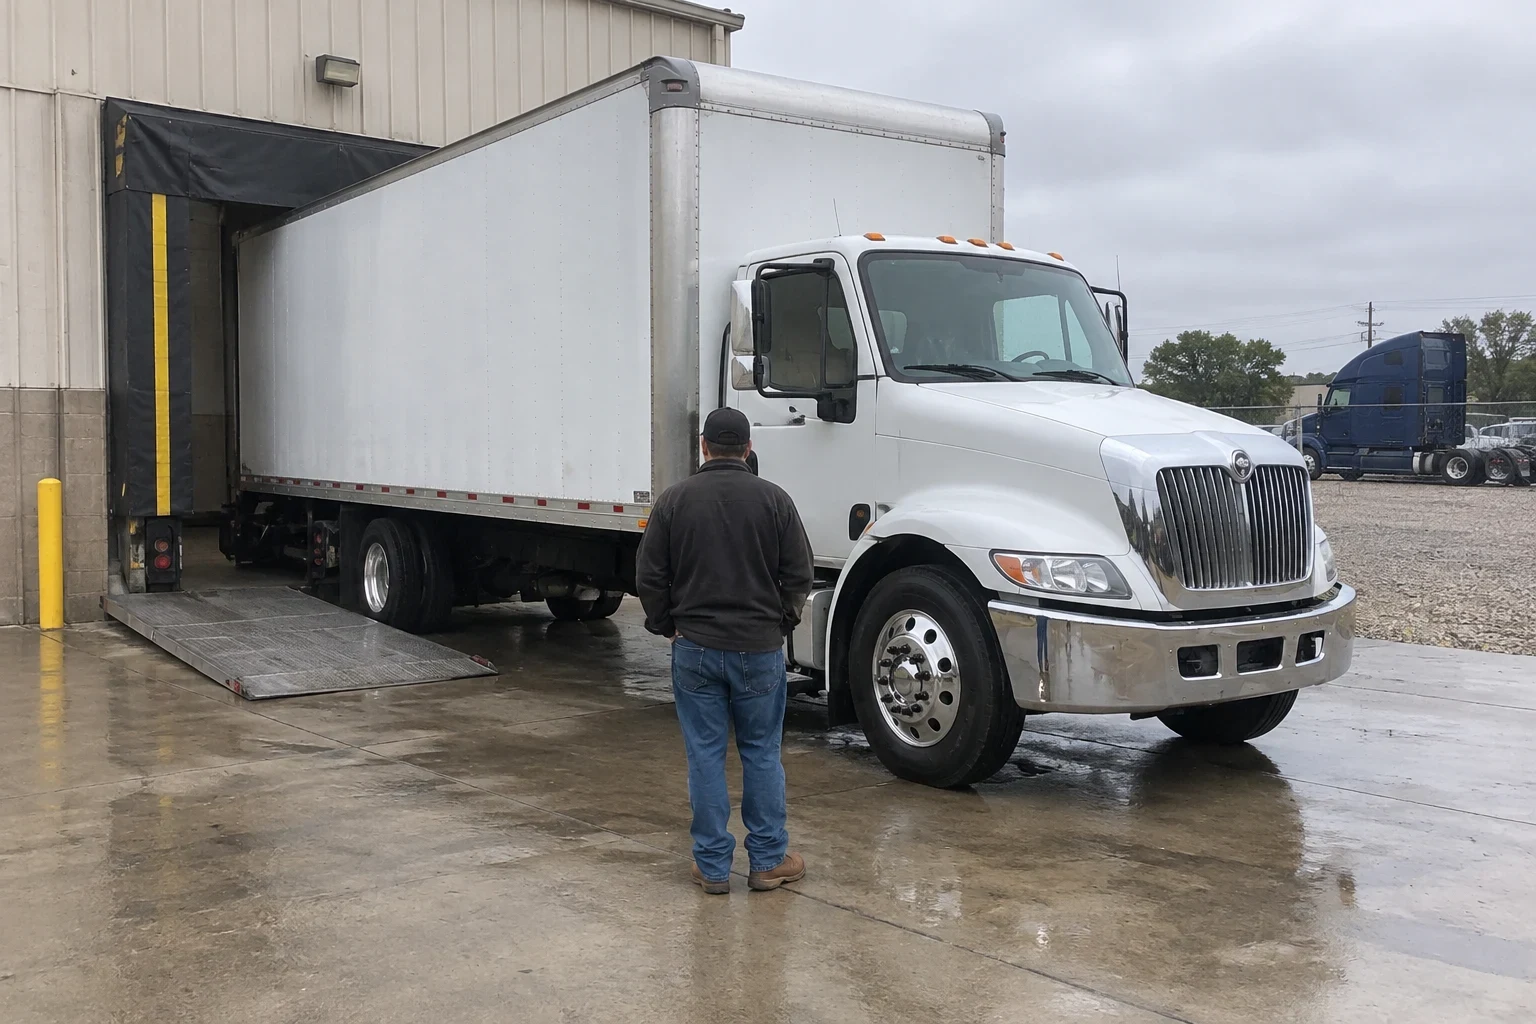
Box Truck Insurance
Liability, cargo and physical damage coverage for 16 to 26 foot box trucks running delivery, moving and freight work, set up to fit your contracts.
Where Our Customers Run From
We work with trucking businesses based in Arlington and the towns around it, including Grand Prairie, Mansfield, Kennedale, Forest Hill and Cedar Hill. We also cover carriers out of Hurst, Euless, Bedford, Richland Hills and North Richland Hills.
- Arlington
- Grand Prairie
- Mansfield
- Hurst
- Forest Hill
- Kennedale
- Richland Hills
- North Richland Hills
- Euless
- Cedar Hill
- Bedford
Since most of our work happens by phone and video, carriers elsewhere in Texas can reach us the same way. See our Service Areas page for more.
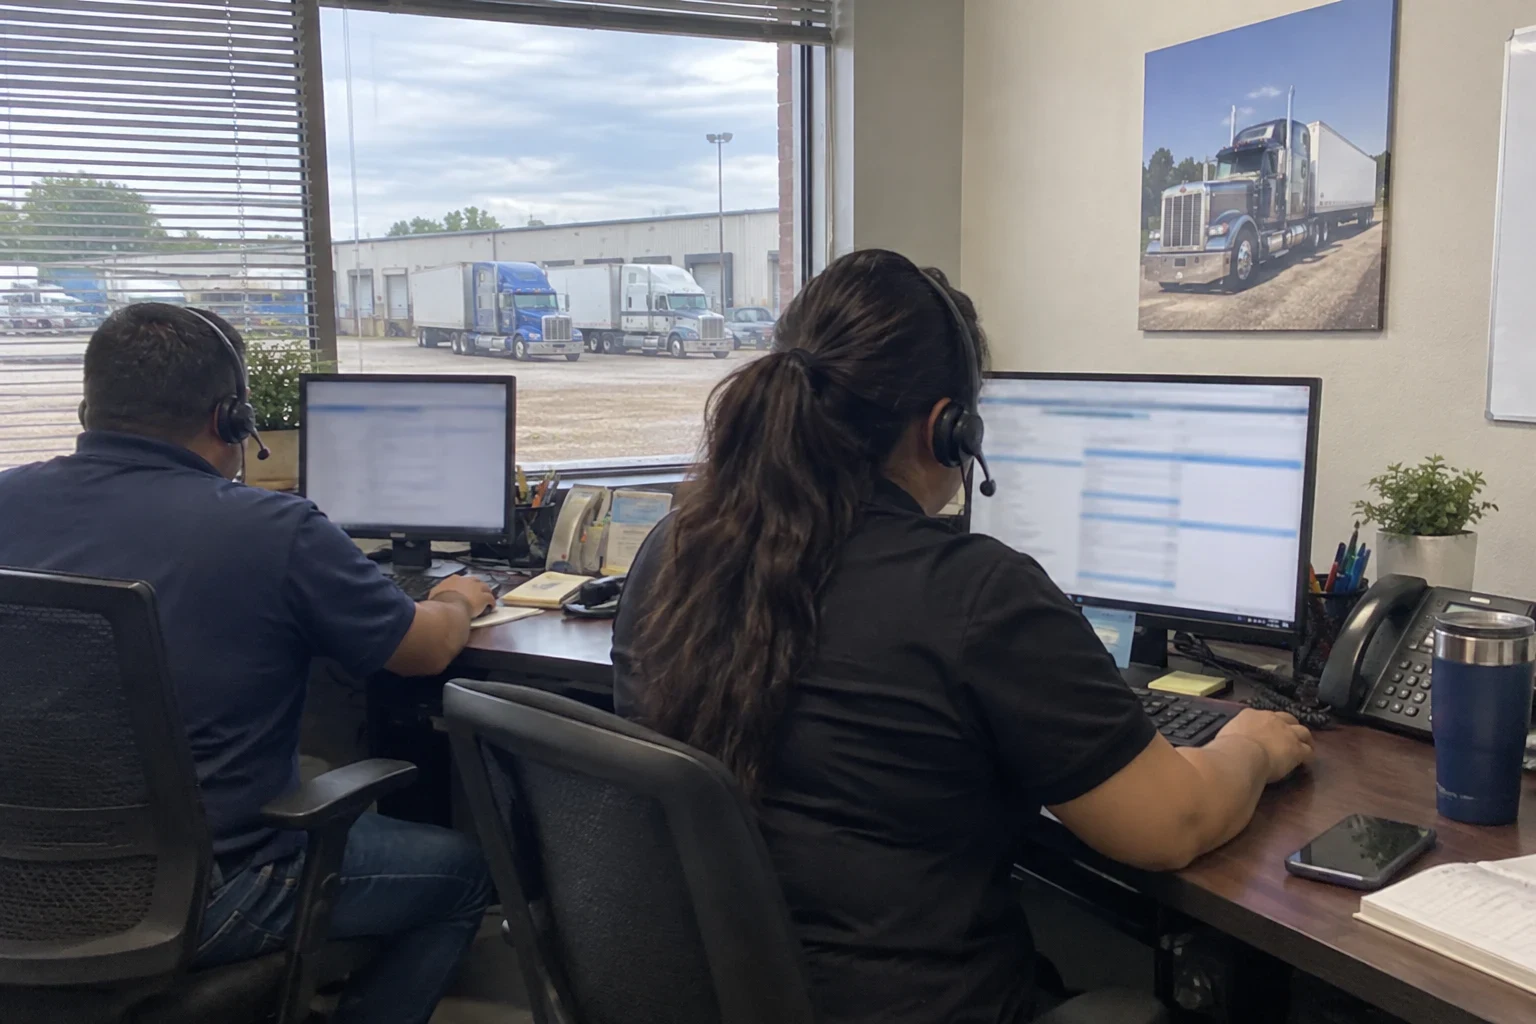
A Trucking Agency in Arlington
We are a small insurance agency that works with trucking businesses. Our customers are owner-operators, people just getting their MC authority, small fleets, and outfits running dump trucks, hotshot rigs and box trucks.
We talk the way you do. When something in a policy matters, we explain it in plain words and tell you what it will cost you if you skip it. When it doesn't matter for your work, we say that too.
Insurance for a truck is a long game. The choices you make in your first year shape your rates for years after, so we set things up with that in mind.
- License
- Licensed for property and casualty insurance
How Getting Covered Works
Most of it happens on one or two calls. You don't need to come by the office, but you can.
- 1
Tell us about your operation
We ask about your trucks, trailers, drivers, DOT number and what you haul. Have your VINs and each driver's CDL details and date of birth handy and it goes faster.
- 2
We shop and compare
We bring back quotes and walk you through them side by side. You see premium, deductibles, limits and the exclusions that matter for your freight.
- 3
Bind and file
Once you choose, we bind the policy and make sure the required filings go to the FMCSA or the Texas DMV. You get your proof of coverage and any certificates you need to start hauling.
- 4
Check in before renewal
Before your policy renews we look again at drivers, equipment and claims. If a change can bring the price down, we tell you before the bill arrives.
What Moves Your Trucking Premium
No two quotes come out the same, because no two operations run the same. Insurers price on risk, and they look at a handful of things every time. Knowing them helps you control the premium over the years, not just this one.
Every quote is built from your drivers, equipment and loads, so we gather those details on the call before we give you numbers. We go over each line with you so nothing on the bill is a surprise.
- Driving records and experience
- Clean MVRs and years behind the wheel of a CDL truck carry the most weight. A single at-fault accident or a few tickets can follow a driver for three to five years.
- Time under your own authority
- New MC authorities pay more until there is a track record. Rates usually ease after the first and second clean years, which is why staying claim-free early pays off later.
- What you haul and how far
- Sand and gravel, general freight, cars on a hotshot trailer and refrigerated loads all price differently. Radius matters too. Local hauling usually costs less than long runs across several states.
- Truck and trailer value
- Physical damage premiums follow the stated value of your equipment. Insuring an older tractor for more than it is worth wastes money, and insuring a new one for too little leaves a gap.
- Limits and deductibles
- Going above the federal minimum on liability or carrying higher cargo limits raises the premium. Many brokers require those higher limits anyway, so we size them to the contracts you want.
- Safety scores and claims history
- Your FMCSA safety data and past claims show up in every quote. Fixing inspection issues now shows up as a better number at your next renewal.
Questions Truckers Ask Us
- What coverage do I need to get my MC authority active?
- For most for-hire carriers hauling general freight, the FMCSA requires primary auto liability with a filing from your insurer. Some freight types need higher limits. Brokers and shippers will often also want cargo coverage before they give you a load. We go over what applies to your freight on the call.
- Why is insurance so expensive for a new authority?
- Insurers have no history on your company yet, so they price for the unknown. Your driving record and CDL experience still help. Staying claim-free and keeping clean inspections usually brings the premium down over the first couple of renewals.
- I'm leased to a motor carrier. Do I need my own policy?
- Usually the carrier you're leased to provides primary liability while you're under dispatch. You will often still need non-trucking liability (bobtail) for when you're off dispatch, plus physical damage on your truck. Check your lease agreement, and we'll read it with you if you're unsure.
- How fast can I get a certificate of insurance?
- Once your policy is in force, call us with the holder's name and any wording the broker asked for. We get the certificate issued and sent to them. Having the broker's request in hand when you call keeps it simple.
- Should I pick the cheapest quote?
- Sometimes, but compare more than the price. Look at the deductible, the cargo exclusions and how the insurer handles claims. A policy that costs a bit more but actually pays on your kind of load is usually the better buy over a few years.
- Does hail damage to my truck get covered?
- Hail is a real risk in North Texas. Physical damage coverage with comprehensive usually pays for hail, minus your deductible. If you only carry liability, damage to your own truck is not covered.
- Do you insure dump trucks, hotshots and box trucks?
- Yes. Each one has its own setup. Dump trucks often need coverage for job sites and contract requirements, hotshot rigs need the trailer and load figured in, and box trucks may run with or without their own authority. We have a page for each one.
Why Truckers Bring Their Policies to Us
A cheap premium that falls apart at the first claim or doubles at renewal is not a deal. We look at the full year, and the one after it.
- We price the deductible, not just the premium
- A higher deductible lowers your premium. It also means more cash out of your pocket after a cracked windshield or a backing claim. We lay out both numbers so you pick the one your bank account can carry.
- Coverage matched to your real loads
- Cargo coverage with an exclusion for the freight you actually haul is money spent on nothing. We read the exclusions against what goes on your trailer, like reefer breakdown, electronics or loose building materials.
- Filings done right the first time
- A missed filing can put your MC authority on hold. We work with the insurer so your federal and Texas filings go in correctly and your DOT number stays active.
- Certificates when brokers ask
- Brokers and shippers want a certificate of insurance before you load. Call us and we get it issued to the right holder with the right wording.
- Straight answers on what you don't need
- If a coverage won't pay off for your setup, we tell you. Leased owner-operators often need bobtail, not a full primary policy, and we explain why.
Get a Policy That Still Fits Next Year
Tell us about your trucks, drivers and loads. We'll show you the options and what each one costs over time.