ServicesMotor Truck Cargo Insurance
Motor Truck Cargo Insurance in Arlington, TX
Cargo coverage pays when the freight in your trailer is damaged, stolen or lost. We match the limit, the deductible and the commodity list to the loads you really haul, so the policy holds up on a bad day and not just on paper.
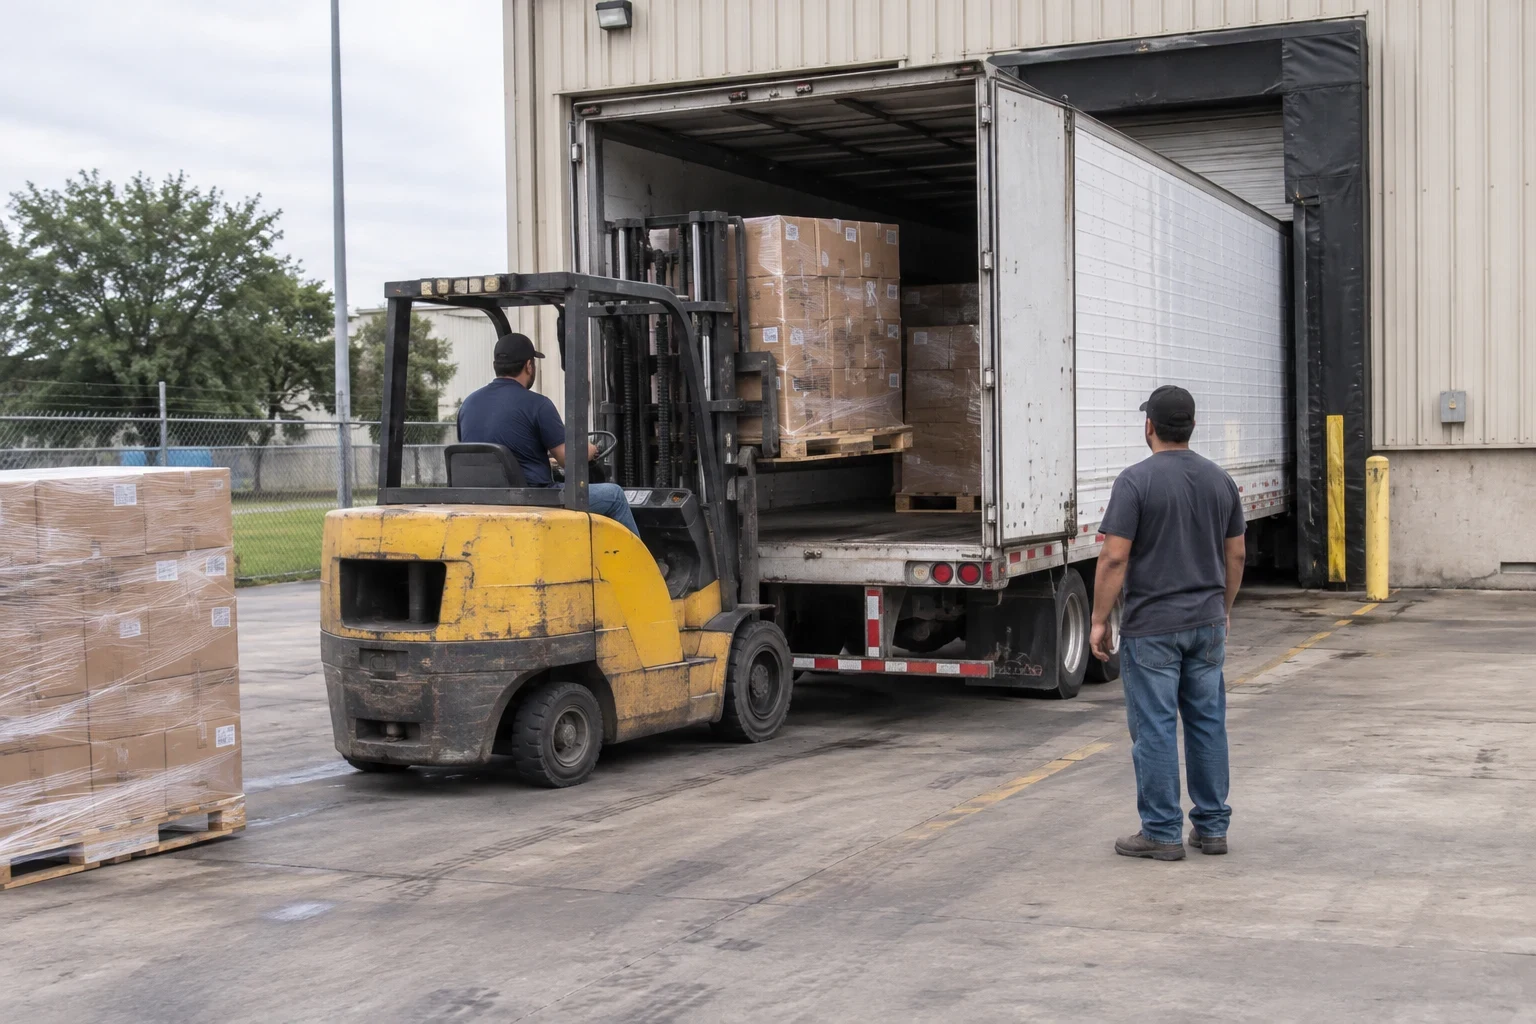
What cargo coverage does for your operation
Motor truck cargo insurance covers the shipper's goods while they are in your care. If a load is wrecked, burned, stolen or ruined in transit, the policy pays the claim so it does not come out of your pocket or your next settlement check. Most brokers and shippers will not tender a load until they see a certificate of insurance showing cargo coverage.
The cheapest cargo policy is often the one that denies the claim. Two quotes can look the same and cover very different things. One may exclude electronics, or theft from an unattended truck, or spoilage when a reefer unit quits. We read those parts with you before you buy, because a slightly higher premium that pays the claim costs less over a year than a cheap one that does not.
We are licensed for property and casualty insurance, and we write cargo coverage for owner-operators, new authorities, fleets, hotshot, box truck and dump operations in Arlington and nearby towns like Grand Prairie, Mansfield and Euless.
What we set up with your cargo policy
- 01
A limit that fits your loads
We look at the highest-value load you haul, not your average one. Brokers set minimum limits in their carrier agreements, and we check that your limit meets them.
- 02
Commodity review
Every cargo policy has a list of excluded or restricted goods. We compare that list to your freight so nothing you haul regularly falls outside the policy.
- 03
Reefer breakdown, if you need it
Spoilage from a refrigeration unit failure is not covered on many base policies. If you pull a reefer, we add reefer breakdown coverage and explain the conditions, like maintenance records the carrier may ask for.
- 04
Theft and unattended vehicle terms
Some policies only pay for theft if the truck was locked, alarmed or parked in a certain kind of lot. We tell you exactly what the wording asks of you.
- 05
Certificates for brokers and shippers
When a broker needs to be listed as a certificate holder, we issue the certificate of insurance so you can get the load booked.
- 06
Fit with your other coverage
Cargo works alongside primary auto liability and physical damage insurance. We make sure the pieces line up so a single wreck does not leave a gap between them.
Questions about Motor Truck Cargo Insurance?
Call(817) 402-2551Signs your cargo coverage needs a second look
A broker turned down your certificate
If a broker says your limit is too low or your policy excludes their freight, you are losing loads. That is fixable, and it usually is not a big change.
You changed what you haul
Moving from dry van to reefer, or from building materials to electronics, can push you outside your commodity list. The policy you bought last year may not fit this year's freight.
You never read the exclusions
Most carriers find the exclusions after a claim. Reading them now takes a short phone call.
Your deductible is higher than you can pay
A high deductible lowers the premium, but you still have to cover it the day a load goes bad. If that number would hurt, it is worth pricing a lower one.
You are running under new authority
New motor carriers often get placed fast just to get rolling. Once you are hauling, it pays to check that the cargo piece actually fits your lanes and freight.
How getting cargo coverage works with us
- 1
A phone call about your freight
We ask what you haul, your highest load value, your equipment and where you run. Have your DOT number and MC authority handy if you have them.
- 2
We shop and compare
We bring back quotes and lay them side by side: limit, deductible, premium and the exclusions that matter for your loads. You see the trade-offs, not just the price.
- 3
You choose and we bind
Once you pick a policy, we bind coverage and handle any filings your authority requires. You can meet with us at our office or by phone and video.
- 4
Certificates when you need them
After the policy is active, call us when a broker or shipper needs a certificate of insurance and we will get it issued to them.
What moves the price of cargo insurance
Cargo premiums depend on how much risk the insurer sees in your freight and your record. We explain each factor so you can decide where spending a bit more now saves money later. A low premium with a narrow policy can cost more over time than a fair one that pays.
- What you haul
- Electronics, metals, alcohol and other goods thieves target cost more to cover. Gravel or lumber usually costs less.
- Limit and deductible
- A higher limit raises the premium. A higher deductible lowers it, but you carry more of each claim yourself.
- Reefer and special coverage
- Reefer breakdown, higher theft limits and broader coverage forms add to the premium. On temperature-sensitive loads in a Texas summer, they are often worth it.
- Your claims and time in business
- Past cargo claims and a short operating history both push the price up. A clean record over a few years helps bring it down.
- Radius and lanes
- Long hauls and certain regions carry more theft and accident exposure than local runs.
Cargo insurance questions we hear
Is cargo insurance required by law?
For most general freight carriers, federal rules do not require it. Brokers and shippers almost always do, though, and their contracts set the limit. In practice, you need it to get loads.
Does cargo insurance cover damage to my truck?
No. Cargo covers the freight only. Damage to your tractor or trailer falls under physical damage insurance, and injuries or damage you cause to others fall under primary auto liability.
What happens if my reefer fails and the load spoils?
That depends on whether your policy includes reefer breakdown coverage. Many base policies leave it out. If you pull a reefer, we will check this first and explain any conditions, such as keeping unit maintenance records.
How fast can I get a certificate for a broker?
Once your policy is active, call us with the broker's details and we will issue the certificate. We do not promise a set turnaround, but we treat these requests as part of keeping you rolling.
Can I raise my limit for one high-value load?
Often, yes. Some insurers allow a temporary increase for a single load. Call before you accept the load so we can check what your policy allows and what it will cost.
Get cargo coverage that fits your freight
Tell us what you haul and what your brokers require. We will walk you through the options and what each one really covers.